 RSS Subscribe
Super El Niño and metals – Richard Mills
The intensifying 2026-27 “Super El Niño” is projected by the World Meteorological Organization (WMO) and the National Oceanic and Atmospheric Administration (NOAA) to be one of the most destructive climate events in 50 years, severely disrupting global metal supplies.
Rather than causing uniform damage, its asymmetric impacts — bringing severe flooding to the Americas and deep droughts across Africa and Asia, threaten up to 25% of global mine supply depending on the asset class.
Because mining operations are highly energy- and water-intensive, extreme weather triggers cascading infrastructure failures, structural power grid blackouts, and localized logistics crises.
Super El Niño
El Niños generally happen every two to seven years and last between nine and 12 months. The second year of an El Niño is often warmer than the first.
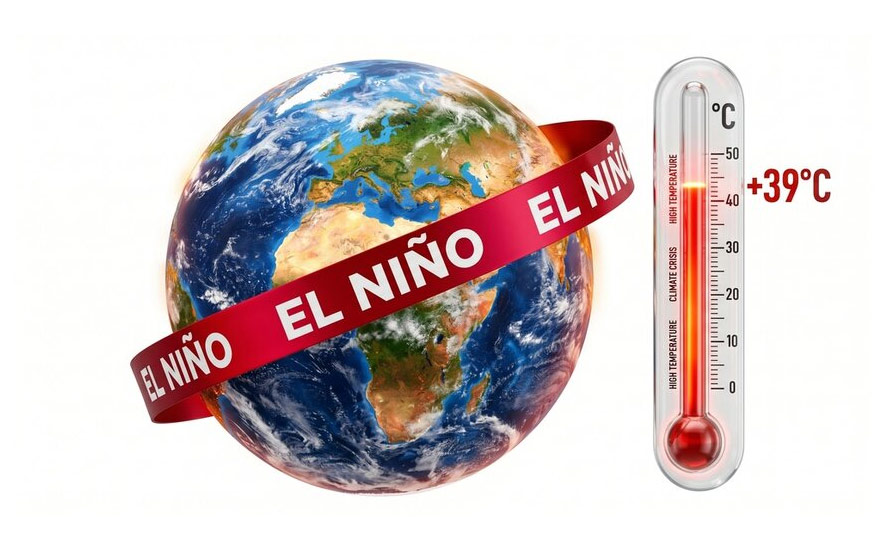
A lingering El Niño is likely to mean a drying trend in places accustomed to rainfall and vice versa, with implications for agriculture, energy and metals.
How does El Niño impact global temperatures? According to the NOAA, it raises heat stored in the Pacific Ocean into the atmosphere, temporarily increasing the Earth’s average temperature on top of long‑term climate warming.
El Niños mainly influences weather in the colder months. During an El Niño winter in the United States, for example, the southern third typically experiences wetter-than-average conditions, while the northern third sees enhanced chances of below-normal precipitation.
They also cause intense rains and droughts across Latin America.
El Niños usually reduce the number of hurricanes in the Atlantic Ocean, particularly the Caribbean. Conversely, El Niño years are typically associated with more activity in the eastern Pacific.
In mid-June, forecasters from the NOAA officially declared that an El Niño was underway. It is set to peak at the end of the year.
A Super El Niño occurs when sea surface temperatures reach at least 3.6F (2C) above the long-term average.
A Super El Nino cometh: Get ready for drought, heat, fires — Richard Mills
WMO forecasts a near-100% likelihood that El Niño will persist through February 2027 and could be the strongest ever, raising risks of extreme weather into next year. Only three very strong or Super El Niños have been recorded since 1950. The last Super El Niño occurred in 2015-16.
Sample Pacific Ocean temperatures in this year’s El Niño are already more than 2 degrees Celsius above normal, said the WMO via Reuters. It adds that 2027 has the potential to exceed 2024’s record-breaking heat.
“Normally after an El Niño event we tend to see a pulse in the global temperatures — a temporary one,” Wilfran Moufouma Okia, the WMO’s chief of climate prediction services, told reporters.
Fractured supply chains

An El Niño or Super El Niño can’t be viewed in isolation. VanEck points out there are other factors already pressuring commodities, including supply chain disruptions:
What sets this El Niño apart from prior episodes, beyond just the severity of the NOAA’s projected effects on the climate, is today’s aggrieved commodity supply chains that have been grappling with multiple disruptions such as the wars in Ukraine and Iran and severe heatwaves across parts of Europe. Given these overlapping pressures, El Niño shouldn’t be read in isolation. More often than not it amplifies or dampens trends already in motion…
A strong 2026-2027 El Niño could amplify already strained commodity supply chains, creating uneven, delayed inflationary pressure across energy, metals, and agriculture markets…
We expect El Niño’s incremental impact on inflation to peak in late 2027 as the market absorbs news of freight disruptions, lower harvests, commodity inventory drawdowns, and potential export restrictions.
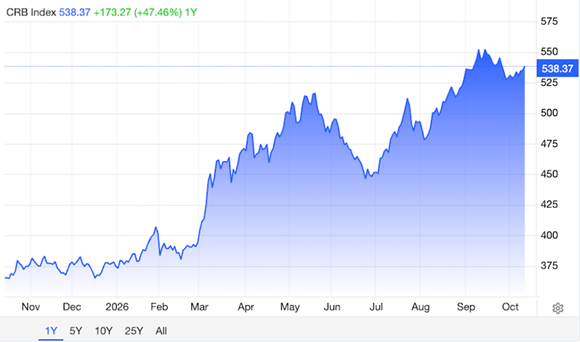
Commodities are already getting expensive. The Bloomberg Commodity Index is up 47% over the last year. The index tracks a basket of 19 commodity futures contracts divided into four sectors: agriculture (includes corn, wheat, soybeans, cotton, coffee, cocoa and sugar), energy (includes crude oil, heating oil, natural gas and gasoline), industrial/base metals (includes copper, aluminum, and nickel) and precious metals gold and silver.
VanEck notes “the damage is already surfacing”, with the Atlantic finishing it first hurricane-free season since 1914; India’s monsoon, the lifeline for roughly half its farmland, entering its final weeks with rainfall 15% less than normal; and water levels in Europe and Latin America falling to critical levels, which is hiking freight costs.
Water levels at the Panama Canal’s locks are sitting below their long-term average, meaning ships must sail lighter and carry less to comply with the Panama Canal Authority’s caps to how deep a vessel may sit in the water.
Kamiar Mohaddes, a macroeconomist and director of the climaTRACES Lab at Cambridge University, said there will be an economic shock if El Niño is strong, citing the pressures the Strait of Hormuz closures have already put on local, regional and global economies.
In particular he said drought in Indonesia would reduce exports of palm oil, coffee and cocoa, and it would also have an impacts on the nickel market because Indonesia is the largest exporters of the battery and steel-reinforcing metal.
Mohaddes said heavy rains would reduce copper output and exports in the number-one-producing country, Chile. That would turn prices higher and “also impacts every single economy in the world, because copper is used now for our net-zero transition and for many things that we’re using. And so that has a negative impact on other economies through supply chain disruptions.”
Finally, Mohaddes noted oil prices increase by an average 15% in an El Niño year, adding to higher prices due to Strait of Hormuz closures. Electricity prices increase if droughts cause less rainfall and reservoir levels fall low, limiting hydroelectric power generation.
Another factor affecting supply chains is the amount of damage likely to be caused by a strong El Niño event, which could number in the trillions of dollars. A Dartmouth College study estimates $84 trillion in economic damage from El Niño cycles over the 21st century. Forbes writes on what an El Niño means for business supply chains and the economy:
Energy markets face further strain from geopolitical conflicts and weather disruptions, potentially driving up oil and gas prices. Food commodities, already affected by fertilizer inflation, will see increased pressure on staples like rice, maize, and wheat due to droughts and extreme heat. Global shipping will be disrupted by altered weather patterns, increased fuel costs, and Panama Canal vulnerabilities. The AI boom’s demand for energy and water will stress infrastructure, impacting silicon chip production and mining. Businesses must diversify energy, build supply chain slack, and regionalize operations to mitigate these cascading risks.
El Niño by region
According to the WMO, this and next year’s El Niño will have asymmetrical effects, with Southeast Asia and northern Latin America experiencing droughts, while southern Brazil and Argentina could see heavy rainfall.
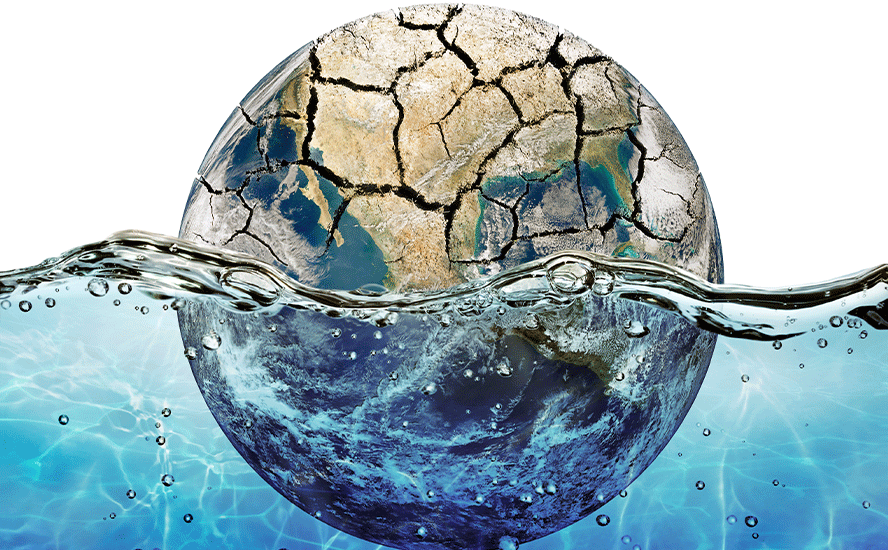
“Above all, El Niño is compounding the effects of global warming and exacerbating existing extreme-weather events (droughts, floods and heatwaves),” states Economic Research by BNP Paribas, a French bank:
In India and South-East Asia, droughts will affect harvests, pushing up prices (particularly for coffee, cocoa, rice and palm oil). Conversely, in southern Brazil and Argentina, heavy rainfall will boost soya and maize production, putting downward pressure on prices.
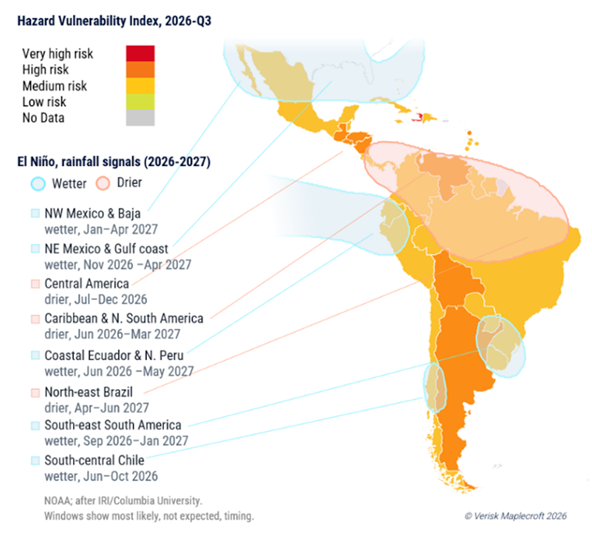
Latin America is facing growing risks of supply chain disruption, commodity production losses and infrastructure stress as a super-strength El Niño intensifies into 2027, according to new research from Verisk Maplecroft.
The global risk data and forecasting company warns the region could face a repeat, or even an amplification, of the devastating 1997-98 El Niño, which triggered an estimated USD$5.7 trillion in global economic losses — almost three times the decline in global GDP during the 2008 financial crisis.
Verisk Maplecroft’s Hazard Vulnerability Index (HVI), which assesses factors such as annual economic loss from natural hazards, natural capital, economic fragility, quality of infrastructure, government effectiveness and the sensitivity of populations, shows the impacts will be unevenly distributed across the region.
While drought threatens Panama Canal traffic, agricultural production, and water security across Central America and parts of northern South America, flooding risks are rising in economically critical regions of Peru, Ecuador and Brazil. These diverging climate impacts are set to create operational challenges across major export sectors, from Central American coffee and maize to Peruvian anchovy and copper, Chilean salmon and Southern Cone soybeans.
“This El Niño is shaping up as a major test for governments, businesses and investors across Latin America,” says Mariano Machado, principal Americas analyst at Verisk Maplecroft. “The resilience of critical logistics, fisheries and agricultural exports, mining operations and energy systems will be severely tested.”
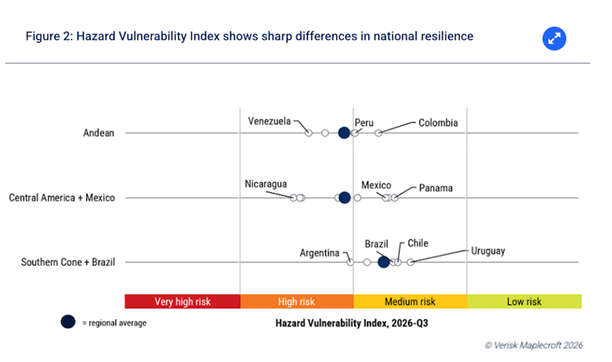
Central America and the Andean region (Venezuela, Colombia, Ecuador, Peru and Bolivia) emerge as the highest-risk subregions overall.
Venezuela, Bolivia and Argentina are the three most vulnerable nations in South America. Colombia, Brazil, Chile and Uruguay are comparatively better placed to absorb El Niño-related disruption.
In Peru, much of the repair and mitigation work from the 2017 El Niño is yet to be completed, meaning this year’s rains in the north and droughts in southern regions will hit farming, industry, and infrastructure even harder.
Mining is particularly sensitive to variations in rainfall: too little restricts output and too much threatens mines and access routes with floods and landslides. Copper prices hit a record USD$6.89/lb on Sept. 9, and any impact on supply could trigger even higher prices.
In contrast, Colombia, with the strongest institutional strength score in the Andean region, has moved to bolster resilience via emergency budget measures aimed at protecting hydroelectric generation and reinforcing disaster-risk management systems.
Central America is expected to experience some of the most severe consequences of El Niño through 2027. The most high-profile impact will be reduced water levels in the Panama Canal, which potentially has very significant consequences for global supply chains. Around 5% of global maritime trade passes through the waterway. Increased restrictions on vessel transits would raise shipping costs, lengthen journey times, and further intensify pressure on logistics worldwide.
In Argentina, increased rainfall could actually benefit soybean and grain-producing regions, as it did in the 1997 event. However, excessive rainfall can also cause flooding in north-eastern and river-basin provinces, which could disrupt planting and growing seasons, as well as roads, railways, storage facilities and access to export terminals.
Brazil is also set to experience greater rainfall in the south and south-east threatening agricultural areas in Mato Grosso, Mato Grosso do Sul, Goiás, Minas Gerais, and Bahia, which account for around 60% of all the country’s soybeans and 70% of all corn production. At the same time, drought in northern and Amazonian regions could constrain river logistics and hydropower generation. Prolonged disruption in these key export markets would tighten global commodity supplies of soy and other crops, increase price volatility, and force international buyers to diversify sourcing.
In Africa, El Niño can drive drought in one area while increasing flood risks in another. Regions such as East Africa and the Greater Horn will be directly affected, states the Institute for Security Studies. In equatorial countries like Kenya, Somalia, southern Ethiopia and Uganda, above-average October-December rainfall is expected. For Southern Africa, below-normal rainfall could occur during the October-April rainy season.
West Africa and the Sahel will likely experience varied impacts. Rather than one extensive drought, unpredictable timing and distribution of rainfall are expected. Parts of Mali, Niger, Nigeria and Chad will experience below-normal rainfall.
An active El Niño affects Australia primarily by driving hotter-than-average temperatures, elevated risks of heatwaves and bushfires, and a tendency toward reduced winter and spring rainfall across the eastern and southern parts of the continent.
However, current conditions in 2026 are unusual: despite a Super El Niño phase developing in the Pacific, warmer-than-average surrounding sea surface temperatures and Indian Ocean moisture have counteracted traditional nationwide drying, leading to mixed and localized rainfall patterns rather than a blanket drought.
This climate pattern is splitting North America into a warmer, drier north and a wetter, stormier south. A powerful high-pressure system will trap Pacific Ocean air across Canada, the Pacific Northwest, the Northern Plains, the Upper Midwest, and the Great Lakes, causing above-average winter temperatures.
Western Canada and the Northern Rockies face less winter snowfall and early snowmelts.
Metals
Metals during a strong El Niño may be impacted by flash flooding, since many mining operations rely on hydroelectric power, including copper mining in Chile. Disruptions risk also exists in Zambia, which could push prices higher.
Forbes notes “Hydro dams may be forced to reduce output or even temporarily shut down due to either extreme rainfall or drought-like conditions. Any stoppage would create cascading shortages all throughout supply chains for both good and services.”

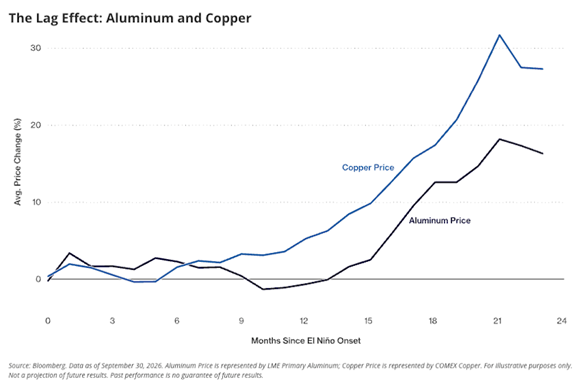
VanEck says Curtailing hydropower generation due to low water levels is a common theme that impacts several commodities. Aluminum smelting runs on cheap power, and a growing share of global production now sits in China’s Yunnan province, home to over 6.0Mt of capacity and a grid that draws roughly 70% of its electricity from hydropower. An El Niño drought tends to drain reservoirs in this province, causing power to run short and smelters to curtail, tightening global supply…
Prices tend to stay soft while El Niño is under way, then firm over the following one to two years as power shortages and curtailments make their mark on supply.
For copper, the El Niño risk is not drought but deluge, and it falls along parts of South America’s west coast where many important mines are located. Chile produces slightly more than 5.0M tons of copper per year, which represents roughly one-fifth of global production. Most of the country’s output comes from its northern regions of Atacama, Antofagasta, and Tarapacá, where heavy rains have disrupted mining and logistics before. During the 2015-2016 El Niño, extreme flooding in Atacama caused considerable damage and downtime to several mines, including Escondida, a mine that comprised 20% of the country’s entire copper output at the time.
Military spending and the metals needed
Nickel and tin are in El Niño’s path, too. Indonesia and the Philippines produce most of the world’s nickel, and both sit in regions El Niño dries out. Indonesia’s smelters, however, run mainly on coal-fired power rather than hydro, which spares them the drought curtailments that hit Yunnan’s aluminum, but leaves producer margins exposed when coal prices climb.
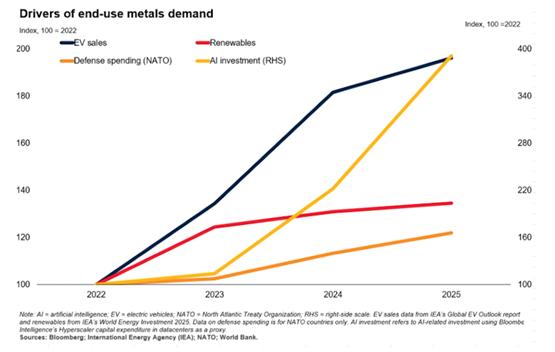
In June, the World Bank Group published a series based on its April 2026 Commodity Markets Outlook. A summary said the base metal price index is projected to reach an all-time high in 2026 led by aluminum, copper and tin, before easing in 2027 while remaining near record levels.
Among the key points:
- Supply constraints have become more pronounced. Base metal production contracted year-on-year in 2026Q1, as the conflict in the Middle East compounded operational disruptions and policy constraints in key producing countries. Aluminum has been particularly affected, given that the Middle East accounts for about 7 percent of aluminum seaborne trade and the sector’s high energy intensity. Meanwhile, China—which accounts for about 60 percent of global output—is nearing its self-imposed 45-million-ton annual production ceiling intended to curb emissions. If maintained, the cap would limit further growth in global aluminum production.
- Copper supply growth has also been constrained by disruptions at major mines, including Indonesia’s Grasberg mine, where output is expected to recover only gradually through late 2027.
- Demand has remained resilient despite slowing global growth. Demand growth for base metals is expected to remain solid, particularly for aluminum and copper, which are widely used in clean energy technologies and digital infrastructure. This resilience partly reflects rising investment in renewable energy and power grids, as well as the rapid expansion of other metal-intensive end uses, including EVs, AI-related data centers, and defense-related manufacturing.
- Base metal prices are set to reach record highs. The World Bank’s metals and minerals price index is projected to rise by 17% in 2026—well above the increase of less than 1% expected in January—and reach an all-time high, before declining by 7% in 2027 as supply conditions gradually normalize. Aluminum, copper, and tin prices are all expected to hit record annual highs in 2026, each rising by about 20%, supported by resilient demand and persistent supply constraints. Nickel prices are forecast to increase by 12% and zinc prices by about 5%, while lead prices are expected to decline slightly. By contrast, iron ore prices are projected to fall in both 2026 and 2027, dropping below their 2020 levels as ample supply continues to outpace weak demand.
- Risks to the price outlook are tilted to the upside. Further supply disruptions linked to the conflict in the Middle East — including through higher energy costs — along with mining setbacks or new trade restrictions, could push prices above baseline projections. Aluminum is particularly exposed, given the Middle East’s role as an important supplier and the sector’s high energy intensity. Copper and nickel could also face pressure from disruptions to key processing inputs, including sulfur and sulfuric acid, amid Middle East supply disruptions and China’s restrictions on sulfuric acid exports. Stronger-than-expected investment in AI-related data centers would further lift demand for aluminum, copper, and other metals. The main downside risk is weaker-than-expected global growth, especially in China, which accounts for about half of global base metal consumption.
Morgan Stanley agrees that Copper output could face disruptions, potentially leading to higher prices. In Chile, the world’s largest copper producer, wetter weather and flooding could pose risks to mining infrastructure. Drought in Zambia, which accounts for 4% of global copper production, could cause hydropower shortages, affecting output.
A recent report by Societe Generale, another French bank, highlights how El Niño 2026-26 could constrain copper output in the African Copperbelt. The belt extends about 450 km northwest from Luanshya, Zambia into the Katanga (formerly Shaba) region of the Democratic Republic of Congo. The zone is up to 260 km wide and contains more than a tenth of the world’s copper deposits.
“With hydropower providing most electricity in the DRC and Zambia, the report warns that drought-driven power shortages and already slowing mine growth may leave Copperbelt production flat at best through H1 2027 before improving later,” the report reads.
Copper going forward: volatile but moving higher
“We estimate rainfall could fall 30cm below last year while temperatures rise almost +1°C, putting additional pressure on river levels and hydropower generation.”
In Chile, GEM Mining Consulting’s Production-at-Risk Index assessed 14 major copper operations across eight threats, with scores ranging from 2.6% to 9%. (Mining.com).
It found El Teniente ranked highest at 9% followed by Los Pelambres at 8% and Escondida at 7.5%.
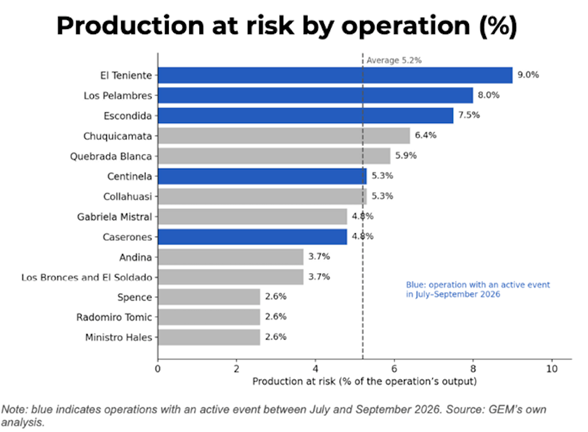
In GEM’s calculations, roughly one in every 20 kilograms of copper expected from Chile’s largest operations depends on the eight identified risks not disrupting output. At El Teniente, the exposure approaches one in 10.
Workers are currently on strike at Antofagasta’s Centinela mine, BHP’s Escondida mine was halted in September due to a fatal accident, and storms disrupted the Los Pelambres and Caserones mines.
When factors such as strikes, severe weather, accidents and geological problems are considered, 5.2% of production at Chile’s largest copper mines are at risk, according to the Production-at-Risk Index.
Chile produced 9.3% less copper from January through July than during the same period in 2025, while July output sank to its lowest monthly level since 2011, the Santiago-based consultancy said via Mining.com.
Effects on inflation
According to the IMF, via BNP Paribas, El Niño causes global food prices to rise by between 5% (in a typical episode) and 8% (very high intensity) year-on-year, with the full impact being felt 6 to 12 months after the climatic peak.
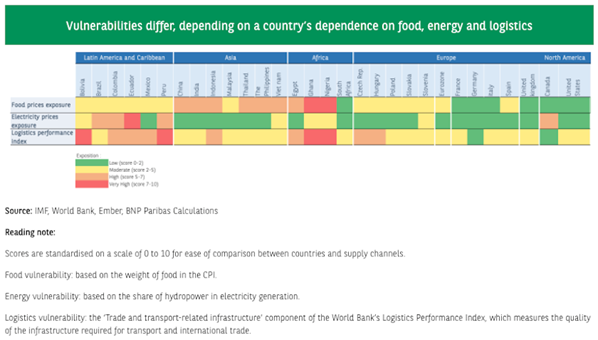
Therefore, for a given country, the weighting of food in its inflation index (CPI) plays a decisive role. As a result, all other things being equal, an 8% rise in prices adds around 1 pp to inflation when food accounts for 13% of the CPI basket (average for countries shown in green on the heatmap), 1.8 pp when this share reaches 22% (yellow), 2.8 pp at 35% (orange) and nearly 4 pp above 49% (red).
Oil spikes groceries skyrocket
The risks are skewed to the upside, as the 8% estimate does not take into account additional losses linked to droughts, floods and other extreme events, while policy responses to shocks (stockpiling by importers and increased export restrictions) may amplify and prolong price pressures. The rice market between 2023 and 2024 illustrates this well, as the combination of rice-export restrictions imposed by India in July 2023 (in order to protect its domestic market) and of the drought in South-East Asia contributed to a 30% average increase in the price of rice over the course of 2023 and kept global prices high for several months after the end of the El Niño episode.
Droughts will reduce hydroelectric power generation in Latin America and South-East Asia. As a result, some countries will have to turn to other, more expensive solutions, such as fossil fuels, against a backdrop of already high oil and gas prices. This shift will increase global demand for oil and put pressure on prices which, according to the IMF, could persist for up to four quarters after the initial El Niño shock…
Therefore, the economies most at risk are not necessarily those that will suffer the greatest climate shock, but those where multiple transmission channels converge, including a high weighting of food prices in inflation, reliance on hydroelectricity, fragile transport infrastructure and limited fiscal room for manoeuvre. Latin America and South-East Asia are home to some of the most vulnerable countries, particularly due to their dependence on food prices and hydroelectricity.
Allianz Trade reports that “a super El Niño would transmit inflationary pressure in Asia primarily through food prices, with Indonesia the most affected (+2.3pp) and Malaysia and the Philippines the most insulated (+0.7pp). In Latin America this picture is mixed, with Colombia, Peru and Brazil facing potential pressures. Central banks in the Philippines, Indonesia and India could be forced to hike further or delay easing into 2027, while Malaysia and Thailand would remain on hold.
Export bans by major agricultural producers (India, Thailand, Vietnam) would ease domestic pressures but amplify inflation risks for importers, notably the Philippines and Indonesia. In Latin America, drought conditions in Northern Brazil and Colombia could push up inflation while Peru could face disruptions from coastal El Niño.”
Conclusion
This El Niño arrives at the worst possible moment. Supply chains already strained by the wars in Ukraine and Iran and by Europe’s heatwaves now face what may be the strongest episode on record, and like the 2015-16 and 2023-24 events, it is likely to push global temperatures to new highs. Heat compounds every other pressure: it cuts labor productivity, raises absenteeism, and drives up electricity demand, with emerging markets hit the hardest. Commodity prices may rise unevenly and with a lag.
Policy response may add fuel to the fire. India has repeatedly restricted rice, wheat, and sugar exports when domestic food prices spike, and this year’s weak monsoon makes a repeat likely, which would tighten global markets further. Ultimately, El Niño will not act alone and may not be the sole driver of commodity price movements, but in this environment, it is more likely to amplify existing pressures. (VanEck)
The surge in base metals is layering onto a wider global commodity shock. With agricultural commodities like sugar, corn and wheat experiencing massive El Niño price spikes, central banks are entering a challenging policy environment. They face a critical supply-side inflation threat that cannot be easily cooled by interest rate hikes without risking broader economic growth.
The dilemma for CBs is they either destroy demand and cause a recession, or they put up with inflation and hope the war in Iran ends and governments slow the printing presses. With US inflation hitting 3.7%, and another rate hike back on the table this month, it was reported Wednesday, I’m betting on higher interest rates, higher Treasury yields, and higher commodity prices.
Staggering US national debt levels and persistent trade deficits mean the US must issue massive amounts of new government debt. Central banks worry about long-term stability, domestic political gridlock, and potential currency debasement if the US prints money to service its obligations.
A comprehensive institutional survey by the Official Monetary and Financial Institutions Forum (OMFIF) revealed that a record 74% of central banks expect to lower their dollar holdings over the next five years, specifically citing rising political risks in the United States.
Data shows that central banks are aggressively choosing physical gold over traditional sovereign debt currencies. According to the Official Monetary and Financial Institutions Forum (OMFIF) Global Public Investor Survey, 82% of central banks now hold physical gold, up dramatically from 71% just a year prior. In fact, gold has officially surpassed US Treasuries to take a larger portion of total global reserve allocations.
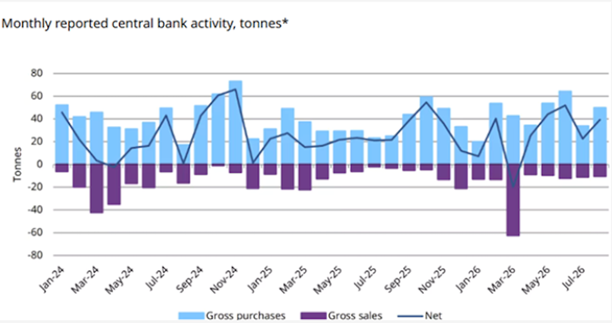
Gold behaves as an early warning system for the economy. When gold prices climb rapidly, it means large institutions and central banks are anticipating that the purchasing power of paper currency is about to drop.
Consumer price increases are driven by structural economic inputs, such as surging crude oil prices hitting $100+ a barrel, manufacturing supply chain bottlenecks, rising corporate wages, or an oversupply of printed fiat currency chasing too few goods.
When those exact inflationary pressures (like high energy costs) start cooking under the surface, investors and central banks run to gold as a historical safe haven. This mass migration pushes gold prices up. Therefore, gold isn’t the fire causing everyday inflation; it is the smoke detector signaling that currency debasement is underway.
That’s why gold ETFs are being snapped up en masse, it’s why gold is holding above $4,100, and it’s why so many commodities are rising in price. The debasement trade is pushing up commodity prices because people no longer trust fiat currency-denominated investments. They want to own something real, and that something is commodities.
Ways to invest include trading commodity futures, buying a commodity ETF, or purchasing shares of junior resource companies, which arguably offer the greatest leverage to rising commodity prices.
Richard (Rick) Mills
aheadoftheherd.com
Legal Notice / Disclaimer
Ahead of the Herd newsletter, aheadoftheherd.com, hereafter known as AOTH.Please read the entire Disclaimer carefully before you use this website or read the newsletter. If you do not agree to all the AOTH/Richard Mills Disclaimer, do not access/read this website/newsletter/article, or any of its pages. By reading/using this AOTH/Richard Mills website/newsletter/article, and whether you actually read this Disclaimer, you are deemed to have accepted it.