 RSS Subscribe
Gold Miners’ Near-Record Q2
Adam Hamilton, CPA
The gold miners will soon report near-record quarterly results, likely their second-best ever. Ongoing high gold prices combined with growing production and lower mining costs will fuel fantastic blowout earnings. Massive Q2’26 profits will drive down already-low gold-stock valuations. Such strong fundamentals along with gold’s coming autumn rally ought to drive a major mean-reversion rebound in this beaten-down sector.
Last quarter was rough for gold stocks technically, with their dominant GDX ETF collapsing 17.8% in Q2 proper! Fully 6/7ths of that plunge happened in June alone, where gold’s multi-month high consolidation failed on heavy selling fueled by irrational Fed-hawkishness fears. Gold plummeted 11.6% in June across three episodes, which hammered GDX 15.7% lower. I analyzed gold’s breakdown extensively in recent essays.
First gold Fed fears flared on a massive upside surprise in monthly US jobs, sparking gold’s initial support failure. Better nonfarm payrolls left traders expecting a Fed rate hike or two later this year into early next. That certainly shouldn’t have slammed gold, as it has thrived through past Fed-rate-hike cycles. And whatever the FOMC does probably won’t even qualify as one, which are defined as three-plus consecutive hikes.
Second gold’s backward war trade resumed after a major escalation in Trump’s war with Iran. That sure didn’t make sense either, as the longer that quagmire festers the higher the resulting inflation which is great for gold investment demand. Third Trump’s new Fed chair came across as hawkish running his first FOMC meeting, focusing on fighting inflation instead of promoting jobs growth. Traders interpreted that way wrong.
Kevin Warsh eliminated forward guidance on the federal-funds-rate trajectory, and will likely soon kill the notoriously-wrong dot-plot projections of it. He knows traders gaming these spawn serious distortions in financial markets. Many times gold has fallen victim to sharp selloffs on those. This new direction for the Fed should liberate gold from years of Fed tyranny! Yet it plunged again on more knee-jerk rate-hike fears.
June’s excessive gold selling in the heart of its weakest time of the year seasonally, the summer doldrums, likely wouldn’t have happened in another month with similar news. June’s low trader interest and low trading volume allow exaggerated price moves. Impressively despite gold’s serious carnage, gold stocks proved quite resilient. GDX’s 15.7% drop last month merely leveraged gold’s 11.6% collapse by a smaller 1.4x.
Typically the major miners dominating GDX amplify material gold moves by 2x to 3x, which would have equated to brutal 23%-to-35% losses last month. Gold stocks’ low valuations sure contributed, with many trading in the low-teens or even single-digit trailing-twelve-month price-to-earnings ratios! Another factor in their defiance was their upcoming near-record Q2’26 earnings. Experienced investors are anticipating them.
Why? The overwhelmingly-dominant driver of gold-mining profits is prevailing gold prices. Despite gold suffering its worst quarter since Q2’13 which hosted another irrational Fed-fear-driven plunge that June, gold still averaged $4,512 in Q2’26. That ranks as gold’s second-highest quarterly average ever, not too far behind Q1’26’s astounding $4,873. Last quarter’s average prices soared a huge 37.3% year-over-year!
This industry’s profits equation is simple, prevailing gold prices less mining costs equal earnings. And the former is way more important and variable than the latter. But predicting mining costs ahead of quarterly reporting is far more involved, requiring vastly more data, experience, and expertise. I’ve painstakingly accrued that over the last 40 quarters in a row, analyzing GDX’s top-25 component stocks’ results in depth.
My last essay on that deep-research thread in mid-May covered GDX Q1’26 results. The best sector measure of mining costs is all-in sustaining costs per ounce. In Q1 the GDX top 25’s AISCs averaged $1,744, extending their four-quarter trend to $1,424, $1,544, $1,661, and that $1,744. Extrapolate these fast-rising costs, and Q2’s GDX-top-25 average would look to come in around $1,850. But that’s very unlikely.
The first quarter in this span, Q2’25, saw GDX-top-25 AISCs skewed low by an extreme outlier making these elite ranks. That was Peru’s Buenaventura, a silver and base-metals miner long masquerading and reporting as a primary gold one. Applying those other much-larger outputs as gold byproduct credits often forces BVN’s gold AISCs deeply negative. In Q1’26 for example, they ran an insane -$5,909 per ounce!
Thankfully Buenaventura now ranks as GDX’s 32nd-largest holding, well outside of top-25 territory for this analysis. Excluding BVN’s absurd AISCs from Q2’25 catapults that GDX-top-25 average up to $1,563, making for a much-more-stable four-quarter trend. Buenaventura fell out of the GDX top 25 in the last three reported quarters, as investors saw through its gold ruse. So it is very unlikely to distort the Q2’26 average.
Another thing to consider predicting AISCs before reporting is the GDX top 25’s average AISC guidance. Gold miners offering that give it early in years covering their entire duration. For 2026, the GDX top 25 are guiding to average AISC midpoints of $1,703. That is under Q1’s $1,744, and plenty of these gold miners forecast higher production in the second half mainly due to expansions and new mines ramping up.
Gold mining unit costs are inversely correlated with output. The more ounces produced, the more to spread the big fixed costs of mining across. And surprisingly global gold mining production predictably varies from quarter to quarter. This is readily evident in the World Gold Council’s data detailed in its fantastic quarterly Gold Demand Trends reports. These offer the best-available gold fundamental data.
The WGC’s latest GDT covering Q1’26 was published at the end of April. Quarterly extending all the way back to Q1’10, worldwide gold-mining production plunged 8.9% sequentially in Q1s, bounced back 5.3% quarter-on-quarter in Q2s, surged 6.7% in Q3s, then stabilized slipping 0.1% in Q4s! Q1s are the production ebb, Q3s the peak. Q2s are the transition between these quarters usually seeing good output growth.
Interestingly gold miners’ production seasonality is mostly weather-related. Over 2/3rds of the planet’s landmass is found in its northern hemisphere, along with a presumably-proportional amount of its gold production. Winter weather ranging from bitter cold up north to heavy rains down south impedes output, primarily by reducing the efficiencies of chemical reactions necessary to recover gold from ores in heap leaching.
Q1s are either the coldest or wettest quarters depending on latitude, and Q3s the warmest and driest. Q2s’ spring weather is much better than Q1s’ winters too, hence global gold output growing 5.3% on average from Q1s to Q2s over the last 16 years or so. If Q2’26’s GDX-top-25 production grows a similar 5% QoQ this year, then AISCs should come in roughly 5% lower than Q1’s. That would imply about $1,657.
That’s well below that GDX-top-25 average 2026 midpoint guidance of $1,703. Yet with Q1’26’s AISCs again coming in higher on lower winter production at $1,744, Q2’s could well print under that midpoint. But to be conservative, let’s assume these elite major gold miners average $1,725 in Q2. That subtracted from last quarter’s awesome $4,512 average gold price would make for huge implied unit profits of $2,787 per ounce!
That would soar a whopping 50% YoY from the comparable Q2’25’s $1,861, and be the GDX top 25’s second-highest on record after Q1’26’s $3,129! And massive gold-mining earnings growth is no flash in the pan. Over the last 11 reported quarters ending in Q1, the GDX top 25’s average implied unit profits have soared an astounding 87%, 47%, 31%, 75%, 74%, 78%, 90%, 78%, 83%, 106%, and 113% YoY!
Holy freaking cow that’s awesome, and probably unparalleled in all the stock markets. These upcoming Q2’26 results from the gold miners are going to prove their 12th consecutive quarter of enormous profits growth, further lowering their already-low valuations. This upcoming Q2 earnings season is going to feel like Christmas for gold-stock investors. I’m super-excited to see, digest, and analyze those results soon.
Given gold miners’ phenomenal sustained windfall-grade profits, their stock prices should be soaring. Yet as this chart shows, they have been crushed in recent months by gold’s serious drawdown. June’s ugly anomalous gold plunge on irrational Fed-rate-hike fears has created what looks like a fantastic gold-stock buying opportunity ahead of both gold miners’ near-record Q2 results and gold’s strong autumn rally mounting.
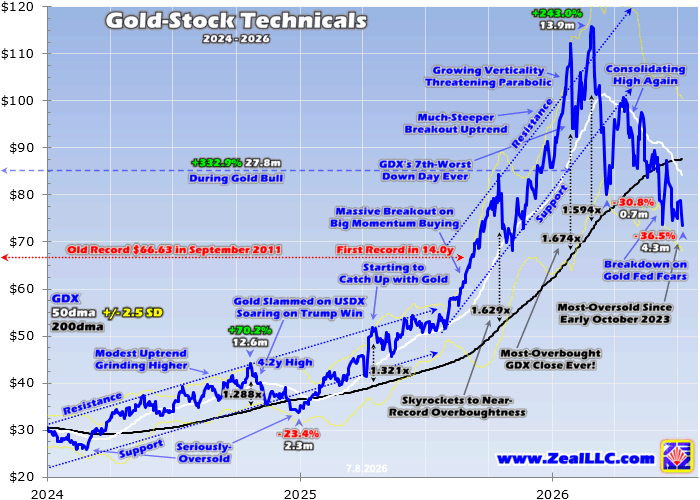
Back in late January as gold soared parabolic in a speculative mania, GDX rocketed up to hit its most-overbought close ever a jaw-dropping 67.4% above its baseline 200-day moving average! After a sharp plummeting, GDX soon soared again into late February to an all-time-record close of $115.84 which was still stretched 59.4% above its 200dma. So gold stocks were certainly due for a big reckoning with their metal.
That came in spades as this sector crashed 30.8% in just 0.7 months into mid-March! Hemorrhaging nearly a third of their value in three weeks should’ve sufficiently rebalanced both extreme technicals and excessively-bullish herd sentiment. Indeed until early June’s gold carnage, GDX held well above that deep March low. But when gold plummeted 3.7% on Jobs Friday June 5th, GDX violently crashed fully 8.8%!
While that was normal 2.4x downside leverage to gold, that shattered GDX’s 2.5-month-old support greatly ramping bearishness. GDX kept falling into June 10th’s 4.3% gold plunge on Trump’s Iran war really escalating, when gold stocks dropped another 4.9% to $73.81! That extended GDX’s total drawdown to 36.3% over 3.4 months. Those new lows held strong until midweek, when GDX plunged again to $73.53.
Gold started recovering nicely in early July heading into its seasonal launchpad starting with its autumn rally. But this Tuesday and Wednesday gold’s backward war trade reasserted itself on Trump’s fragile ceasefire with Iran imploding. Gold only fell a relatively-mild 1.2% and 0.8% on those two days, but gold-stock traders panicked hammering GDX 3.7% and 3.0% lower! That unjustified selling was way overdone.
That marginally worsened gold stocks’ drawdown to 36.5% over 4.3 months, and pounded GDX back down to just 84.0% of its 200dma. That was the most oversold gold stocks have been in fully 2.8 years since early October 2023, the very day GDX carved a major secular low birthing recent years’ massive gold-stock bull. From then until late February 2026, GDX more than quadrupled soaring 347.1% higher!
And because gold miners’ earnings have skyrocketed so mightily in recent years, their valuations have collapsed despite way-higher stock prices. Just after Q4’23’s earnings season where their last bull was born, the GDX top 25 averaged 49.6x TTM P/Es. That plunged nearly 6/10ths to 20.2x in mid-May 2026 right after Q1’26’s results! Again today plenty of great gold miners are sporting low-teens or single-digit P/Es.
Since Q2’26’s profits are tracking about 50% higher year-over-year, they will force P/Es lower still as Q2’25 results roll off the trailing-twelve-month calculation. Low valuations heading even lower with gold stocks the most oversold they’ve been since their last massive bull was born heading into near-record quarterly results sure seems like a potent recipe for a major sector rally! This sure looks like a fantastic buying op.
So despite June’s extreme volatility forcing vexing stoppings, we’ve been aggressively adding new trades in fundamentally-superior smaller mid-tier and junior gold stocks in our subscription newsletters. They tend to well outperform the majors during gold uplegs, achieving better production growth often at lower mining costs. We’re zeroing in on smaller miners mostly with great production growth profiles in coming years.
Gold-stock prices could easily double from current battered levels and still be reasonably valued relative to their underlying earnings streams. Of course when and how much they surge will depend on how gold fares, and it also just hit its own most-oversold levels in 3.7 years in late June! Gold is due for a powerful mean-reversion bounce heading into Q2’s earnings season for the miners, which ought to spark some fireworks.
The bottom line is gold miners will soon report near-record results, with Q2’26 proving their second-best quarter ever. Last quarter’s ongoing high prevailing gold prices combined with stable mining costs and rising production will fuel fat windfall profits. This will be gold miners’ 12th consecutive quarter of huge earnings growth, forcing their already-low valuations even lower attracting more interest from smart investors.
Yet gold-stock prices were just slammed to their most-oversold levels since their last mighty bull was born several years ago. This stark technical disconnect between battered stock prices and fantastically-bullish fundamentals soon to be reconfirmed makes for a heck of a buying opportunity. And gold’s autumn rally getting underway from its own recent secular-low oversoldness should really light a fire under its miners’ stocks.
Adam Hamilton, CPA
July 10, 2026
Copyright 2000 – 2026 Zeal LLC (www.ZealLLC.com)
Legal Notice / Disclaimer
Ahead of the Herd newsletter, aheadoftheherd.com, hereafter known as AOTH.Please read the entire Disclaimer carefully before you use this website or read the newsletter. If you do not agree to all the AOTH/Richard Mills Disclaimer, do not access/read this website/newsletter/article, or any of its pages. By reading/using this AOTH/Richard Mills website/newsletter/article, and whether you actually read this Disclaimer, you are deemed to have accepted it.