 RSS Subscribe
De-dollarization but for the lack of an alternative – AOTH
Central banks are actively diversifying their foreign exchange reserves away from the U.S. dollar.
Dedollarization refers to a strategic economic process where governments, central banks, and market participants reduce their reliance on the U.S. dollar (USD) for international trade, foreign exchange reserves, and bilateral transactions.
For decades, the U.S. dollar has served as the world’s primary global reserve currency. Dedollarization occurs when countries actively shift toward alternative currencies (like the Euro, Chinese Yuan, or local currencies) or tangible assets (like gold) to settle debts and store national wealth.
Countries typically pursue dedollarization due to a combination of geopolitical, strategic, and macroeconomic factors:
The weaponization of the USD financial system (such as freezing central bank reserves or disconnecting nations from the SWIFT network) pushes sidelined nations to find alternative payment rails.
Relying entirely on one currency exposes global economies to domestic U.S. monetary policy changes, inflation, and political instability.
As emerging economies grow, blocks like BRICS actively promote utilizing local currencies for cross-border trade to bypass USD conversion costs.
To track the progress of dedollarization, economists measure the dollar’s share across three primary pillars: Foreign Exchange Reserves, Global Trade Invoicing, and International Debt/Liquidity.
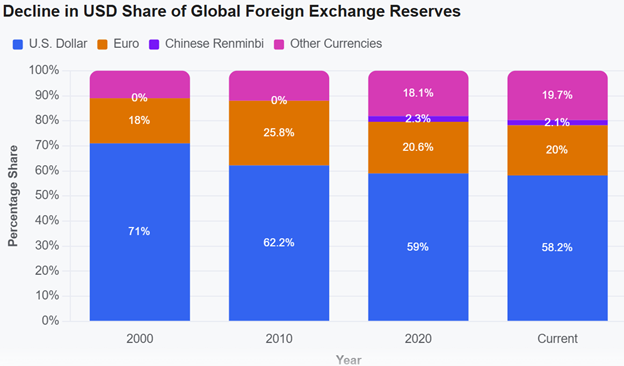
While the USD’s share in central bank reserves has gradually decreased over the last two decades, it still maintains a dominant lead in global payments and trade.
Understanding what dedollarization isn’t helps clarify its actual impact on the global stage:
It is a slow, structural shift playing out over decades, rather than a sudden displacement of the U.S. financial system.
The goal for most nations is diversification and autonomy, not a complete ban on holding or trading in USD.
No single currency currently possesses the liquidity, open capital markets, and legal protections required to fully replace the USD as a singular global standard.
Historical precedent
The most striking historical precedent for modern de-dollarization is the transition of the global reserve currency from the British Pound Sterling (GBP) to the U.S. Dollar (USD) during the 20th century.
For nearly a century, the British pound was the undisputed anchor of international commerce. Its displacement was not a sudden overnight collapse, but a gradual multi-decade process driven by war, shifting macroeconomic power, and heavy debt accumulation.
By the late 1800s, Great Britain’s Industrial Revolution had made London the undisputed center of global trade and finance.
The vast majority of global trade was invoiced in pounds, and central banks held their wealth in sterling because it was directly convertible to gold.
Even though the U.S. economy surpassed Britain’s in size by the 1880s, the pound maintained its reserve status. This highlights how “inertia” keeps a legacy currency dominant long after an economy has been eclipsed
The structural shift began in earnest with World War I.
To finance the war, Britain borrowed heavily from the United States, transitioning from a global creditor to a debtor nation.
While Britain had to temporarily suspend its gold standard to pay for the war, the U.S. dollar remained continuously tied to gold. By the mid-1920s, the U.S. dollar was openly competing with and occasionally surpassing the pound in central bank reserve holdings.
World War II dealt the final economic blow to Britain’s currency empire. Severely depleted by the war, Great Britain could no longer sustain its global financial architecture.
Conclusion
There are several striking similarities between the challenges facing the U.S. dollar today and the conditions that triggered the decline of the British pound. However, there are also structural differences that make a total dollar collapse unlikely anytime soon.
Economists point to clear parallels in skyrocketing national debt and geopolitical friction, balanced by a major difference: the modern dollar lacks a clear, single successor like the U.S. was to Britain.
Following the World Wars, Great Britain suffered from deep structural financial imbalances. Today, the United States is facing a massive expansion of national debt, with gross federal debt exceeding $40 trillion and a gross debt-to-GDP ratio standing at about 126%. Net interest payments consume nearly 15% of all federal spending, mirroring the fiscal strain that historically weakened the pound.
Just as the global economy fragmented into the British-led “Sterling Area” and outside markets, modern geopolitics is seeing a clear divide. The weaponization of the dollar via aggressive financial sanctions (such as freezing Russia’s central bank reserves in 2022) has forced rival blocs like BRICS to build independent cross-border payment solutions to protect their financial sovereignty.
The pound didn’t vanish instantly; it gradually lost ground. The U.S. dollar is currently tracking a similar pattern. The IMF’s Currency Composition of Official Foreign Exchange Reserves shows the dollar’s share of global reserves hovering at roughly 56.7%, down significantly from around 70% in 2000.
While the structural vulnerabilities align, the global landscape looks different in one vital way: the lack of a single, scalable alternative.
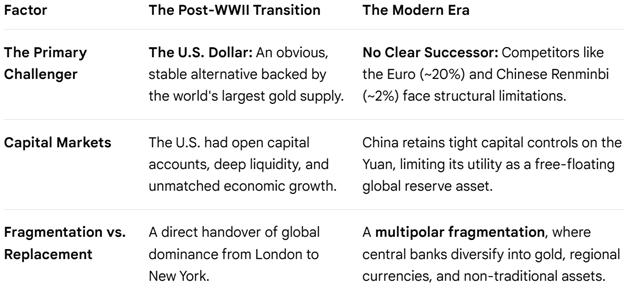
Today’s conditions match the internal decay that ruined the pound, mainly unsustainable debt and geopolitical overreach. However, because the rest of the world has no trusted, highly liquid, single alternative to turn to, the dollar’s erosion remains a slow, fragmented drift rather than a sudden displacement.
Legal Notice / Disclaimer
Ahead of the Herd newsletter, aheadoftheherd.com, hereafter known as AOTH.Please read the entire Disclaimer carefully before you use this website or read the newsletter. If you do not agree to all the AOTH/Richard Mills Disclaimer, do not access/read this website/newsletter/article, or any of its pages. By reading/using this AOTH/Richard Mills website/newsletter/article, and whether you actually read this Disclaimer, you are deemed to have accepted it.